The building
In a pure land value tax, improvements sit outside the tax base.
Land · Housing · Public revenue
Every address has a value. Where does it come from?
A tax on the value of a site. Buildings and other improvements are excluded. [01]
Before exemptions, reliefs or other charges. [05]
01 / Where value comes from
A station, a school, nearby jobs. The surroundings help determine what people will pay for a location. Land value taxation draws public revenue from that value. [03]
In a pure land value tax, improvements sit outside the tax base.
Keeping a valuable site empty does not remove the charge on its land value.
Services, lower taxes elsewhere, or other spending: the use of the money is a separate decision.
02 / Try the numbers
Two hypothetical plots, each with land worth €200,000. Move the slider to change the building on plot B.
Land value €200,000
Land value €200,000
| Annual tax | Plot A | Plot B | Total |
|---|---|---|---|
| Land + buildings1% property tax | €2,000 | €6,000 | €8,000 |
| Land only2% land value tax | €4,000 | €4,000 | €8,000 |
At the starting values, both systems raise €8,000 in total.
Illustrative amounts in eurosIn this example, construction changes the property-tax bill. The land-tax bill stays the same.
03 / Around the world
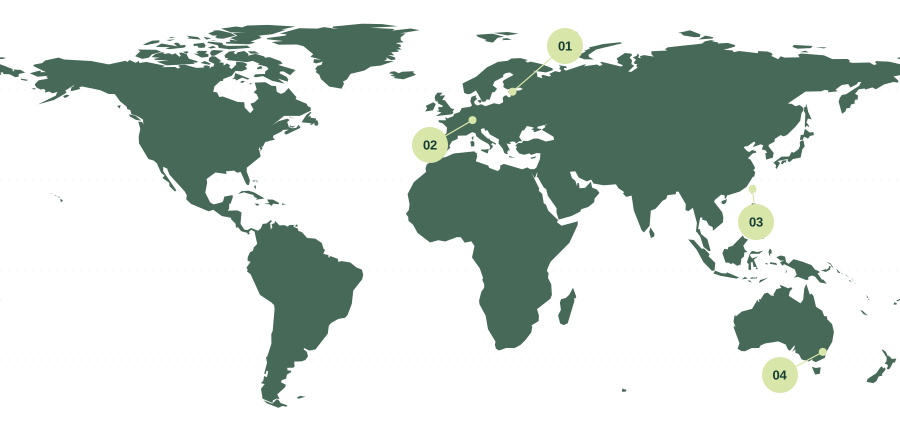
Land-based taxes already operate in several places. Their rates, exemptions and relationship to other taxes differ.
National land tax
Land is taxed on its assessed value. Local rates, reliefs and limits on increases affect the bill. [05]
Germany · Since 2025
Its modified land-value model uses plot area and a standard land value. Residential use receives a reduction. [06]
Annual land value tax
Assessed land values form the tax base. Special rates and agricultural rules shape who pays. [08]
Australia · Reform since 2012
A long-running reform shifts revenue from transaction taxes towards broad-based, land-based rates. [07]
04 / The evidence
The tax design is specific. Its wider effects depend on the place.
A 2026 review prepared for the Welsh Government found limited, context-dependent empirical support for many broad LVT claims. Development effects depended on demand, planning and tax design. [09]
Read the evidence reviewopens a new tab05 / Questions worth asking
Explore the details
Land values, household incomes, planning rules and existing taxes all affect how a reform would work. [09]
Follow the sources
Official rules, economic analysis and an advocate’s perspective. Sources are linked beside the claims they support.
C2PA / Content Credentials
This page was made with AI assistance. Its four photographic-style illustrations depict imagined places. All eight image files contain signed C2PA Content Credentials with the publisher’s AI-generation disclosure.
These credentials are signed by the publisher using a private certificate authority. The signer is not on the public C2PA trust list and is not independently verified. The signature makes later changes detectable; it does not prove the text is accurate or establish the original model, prompt or creation date.
Download an image and open it in a C2PA inspection tool. The JSON reports below were generated from the signed files. They are readable records, not a substitute for verifying the image. Reports and downloads require the hosted site.